

A CRM for financial services is a client relationship platform configured around the way financial firms manage people, households, entities, advice, lending, compliance, and long-term service relationships. Microsoft Dynamics 365 can provide a strong foundation for this model, but it usually needs careful configuration so it reflects financial workflows rather than a generic sales pipeline.
You may need a specialised financial CRM when spreadsheets, inboxes, disconnected systems, or basic sales tools start limiting service quality. Common warning signs include advisers manually chasing documents, client data living in multiple places, compliance reviews being tracked outside the CRM, and leadership struggling to get reliable reporting across advice, lending, banking, or service teams.
Decision point: If your team cannot quickly answer “who is this client, what do they own, what advice or service have we provided, what is outstanding, and who else in the household or business is connected?” your CRM model may be too basic for financial services.
Unlike standard sales tools, a financial CRM can act as a unified hub that understands the financial context of each contact. It can link individuals to their families, businesses, trusts, and self-managed super funds (SMSFs), while tracking goals, risk profiles, communication history, onboarding tasks, and compliance activity where those workflows are configured.
I’m Warren Davies, founder of Beyond CRM. I bring practical experience in helping organisations design, customise, and adopt Microsoft Dynamics 365 CRM solutions that fit their real operating needs. My perspective in this guide is shaped by the challenges financial services teams often face when client data, compliance activity, service workflows, and reporting need to work together in one connected CRM environment.
The Limitations of General-Purpose CRMs
General-purpose CRMs can work for simple lead tracking, but financial firms often hit limits when they need to manage complex client relationships, regulated processes, and multi-department service delivery. Without suitable financial data structures, firms may need heavier customisation, manual workarounds, or disconnected specialist tools.
This can lead to:
- Higher development and maintenance costs when custom entities are needed for portfolios, policies, applications, reviews, and compliance checks.
- Workflows that are harder to maintain when processes change or vendor updates affect custom fields and integrations.
- Lower user adoption if advisers must complete too many non-intuitive fields just to record a meeting or update a client file.
- Inconsistent reporting when data is entered differently across teams.
A purpose-built financial CRM configuration can reduce these issues by giving teams a practical data model for the way financial professionals actually work. For firms using Microsoft technology, that often means tailoring Dynamics 365 around financial services workflows instead of forcing advisers, brokers, and service teams into a generic sales process.
The Power of Householding and Relationship Mapping
One of the most important differences between a generic CRM and a financial services CRM is relationship mapping, often called householding. This matters because a single client rarely exists in isolation.
They might be:
- The head of a household.
- A director of a proprietary limited company.
- A trustee of a family trust.
- A beneficiary of an estate.
- A borrower, investor, policyholder, and advice client at the same time.
A generic CRM may treat these as separate, disconnected accounts. A financial CRM can map these relationships clearly so advisers and service teams can understand the client’s broader financial picture, identify related service needs, and reduce fragmented advice or support.
Creating a 360-Degree Client View Across Financial Services
A complete 360-degree client view brings banking, lending, wealth management, advice, service, documents, interactions, and compliance activity into one connected record or accessible view. This does not mean every system disappears; it means the CRM becomes the central relationship layer that connects data from core financial platforms, planning tools, portfolio systems, document storage, and communication channels where integrations are appropriate.
For example, a relationship manager should be able to see a client’s household structure, open lending opportunities, recent service cases, upcoming review dates, and adviser notes without switching between multiple disconnected systems. That shared view can help teams deliver more consistent service and gives leaders a better basis for pipeline, retention, and compliance reporting.
Why Do Financial Institutions Need a Dedicated CRM System?
Financial institutions need a dedicated CRM system to centralise client data, streamline operations, and support rising digital expectations. The goal is not just to store contact details; it is to support complex client lifecycles, regulated workflows, and long-term relationship retention.
The financial services landscape is shifting rapidly. Wealth is moving between generations, clients expect more personalised digital experiences, and internal teams are under pressure to provide faster service with stronger compliance oversight. In that environment, disconnected data can create both service friction and operational risk.
CRM investment may translate into measurable business outcomes when the system is designed around the firm’s real workflows. For example, improved onboarding, better follow-up discipline, cleaner reporting, and more coordinated service can help teams convert more opportunities and retain stronger client relationships. To see how these principles apply specifically to banking, read our guide on CRM for Banking Sector.
When a Financial Firm Has Outgrown Spreadsheets
Many firms start with spreadsheets because they are flexible and familiar. The problem is that spreadsheets become unreliable once multiple advisers, administrators, lending specialists, and service teams need to work from the same client information.
Signs you may have outgrown spreadsheets include:
- Client review dates are missed or tracked manually.
- Document requests are managed through email threads.
- Different departments maintain separate versions of the same client record.
- Compliance evidence is difficult to retrieve.
- Managers cannot trust pipeline, service, or retention reports.
At that stage, a CRM becomes less of a sales tool and more of an operating system for client relationships.
Streamlining the Client Onboarding Experience
First impressions matter. Historically, onboarding a new client in financial services has often been slow, paper-heavy, and full of duplicate data entry.
A modern financial CRM can support onboarding by automating selected administrative steps. When a prospect becomes a client, the CRM may trigger digital workflows, assign document collection tasks, send secure links for forms or signatures, and pre-populate records using information already captured during discovery, depending on the firm’s configuration and connected systems.
This can reduce manual administration for staff and accelerate time-to-value for new clients. It also creates a more consistent onboarding process, which is especially important when firms need to show that required disclosures, identity checks, and internal approvals were completed.
Improving Cross-Department Collaboration
In many financial institutions, departments operate in silos. A retail banking team may not know what the lending team is doing, while wealth advisers and customer service representatives may rely on separate notes, systems, or spreadsheets.
A unified CRM can help maintain consistent client data across departments by giving each team an appropriate view of the same underlying relationship record. A commercial banker can see relevant lending activity, a service representative can view recent adviser notes, and an adviser can understand unresolved service issues before a review meeting, subject to permissions and data-sharing rules.
This does not mean every team sees every sensitive field. A well-designed CRM uses role-based security, field-level controls, and structured data models so teams can collaborate without compromising privacy or compliance.
How Does a Financial CRM Help with Compliance, KYC, and AML Requirements?
A financial CRM supports compliance, KYC, and AML requirements by structuring regulatory workflows, tracking document status, and helping secure sensitive client data. This can help firms manage risk and maintain audit readiness without relying only on informal reminders or disconnected spreadsheets.
In financial services, compliance is part of daily operations. A dedicated financial CRM should make required steps visible inside the normal client workflow, so advisers and administrators can see what has been completed, what is overdue, and what evidence is stored against the client record. For a deeper look at protecting sensitive information, see our guide on CRM Data Security Best Practices.

Automating KYC and AML Workflows
KYC and AML processes often involve multiple steps: collecting identity documents, verifying information, recording risk ratings, checking expiry dates, escalating exceptions, and documenting approvals. A financial CRM can help automate parts of these workflows by turning them into structured tasks and status fields rather than informal email chains.
For example, the system can be configured to flag when KYC documentation is approaching expiry, assign a task to the relevant team, and prompt staff to request updated information through an approved process. Where the CRM is integrated with document management, identity verification, or client portal tools, supporting evidence can be linked back to the client record.
Practical question: Can a CRM automate compliance completely? No. A CRM supports the workflow, evidence trail, reminders, and controls, but your firm still needs appropriate policies, human review, and regulatory oversight.
Protecting Sensitive Financial Data
Financial institutions handle sensitive personal and financial data, including tax file numbers, bank account details, net worth statements, income information, and advice records. To protect this information, the CRM architecture should include strong access controls and careful data governance.
A properly configured financial CRM can provide:
- Role-based access control so employees only see information relevant to their responsibilities.
- Field-level security for highly sensitive data.
- Audit logs that record who accessed or changed key information.
- Structured retention and review processes for documents and client records.
- Integration patterns that avoid unnecessary duplication of sensitive data across systems.
The right configuration is especially important in Microsoft Dynamics 365 environments because the platform is flexible. That flexibility is valuable, but it also means security roles, data models, environments, and integrations need to be designed carefully from the start.
How Do Different Departments Use a CRM in a Financial Services Firm?
Different departments use a financial CRM to access a single source of truth while working through role-specific processes. The same CRM can support advisers, lending teams, banking teams, customer service, compliance, and management if the data model, permissions, and workflows are designed correctly.
A unified financial CRM is not just a tool for advisers. It is an enterprise-wide platform that connects front, middle, and back-office activity so everyone works from consistent information.
Wealth Management and Financial Advisers
For wealth managers and financial advisers, the CRM is the operational cockpit of the practice. It should help them prepare for meetings, record advice activity, manage follow-up tasks, and understand the client’s household, goals, preferences, and review history.
Common Dynamics 365 customisations for financial advisers include:
- Household and relationship mapping.
- Financial goal, risk profile, and review tracking.
- Advice opportunity and service pipeline stages.
- Document checklists and disclosure workflows.
- Meeting note templates and follow-up task automation.
- Integration with Outlook, Teams, planning software, and document storage.
These customisations reduce adviser administration by making the next action clear and keeping client context close to the workflow.
Lending and Mortgage Teams
Lending professionals use the CRM to manage enquiries from initial contact through to approval, settlement, and post-settlement service. A financial CRM can track loan stages, required documents, credit assessment tasks, referral sources, and partner updates.
This is where one CRM can support multiple departments without creating confusion. Lending teams may use different forms, fields, and process stages than advisers, but the underlying client record can still remain connected. That makes it easier to identify relationships between borrowers, business owners, households, and wealth clients.
Customer Service and Support Teams
When a client contacts the firm, they expect a fast, informed response. Customer service teams use the CRM to view relevant relationship history, log cases, route issues, and escalate complex matters to advisers, lending specialists, or compliance staff.
The key is to design service processes that support the financial relationship rather than treating each enquiry as an isolated ticket. If a service team can see recent advice meetings, open lending applications, and unresolved document requests, they can respond with more context and reduce unnecessary back-and-forth.
Leadership, Compliance, and Operations
Executives, compliance managers, and operations leaders use the CRM differently again. They need reliable dashboards showing pipeline health, client onboarding progress, outstanding reviews, service volumes, adoption levels, and workflow bottlenecks.
Manual reporting is a major warning sign that the CRM is not yet serving as a true operational platform. When data is structured correctly, leaders can see performance across departments without asking teams to prepare separate spreadsheets each month.
Why Are Integrations and CRM Architecture Critical in Financial Services?
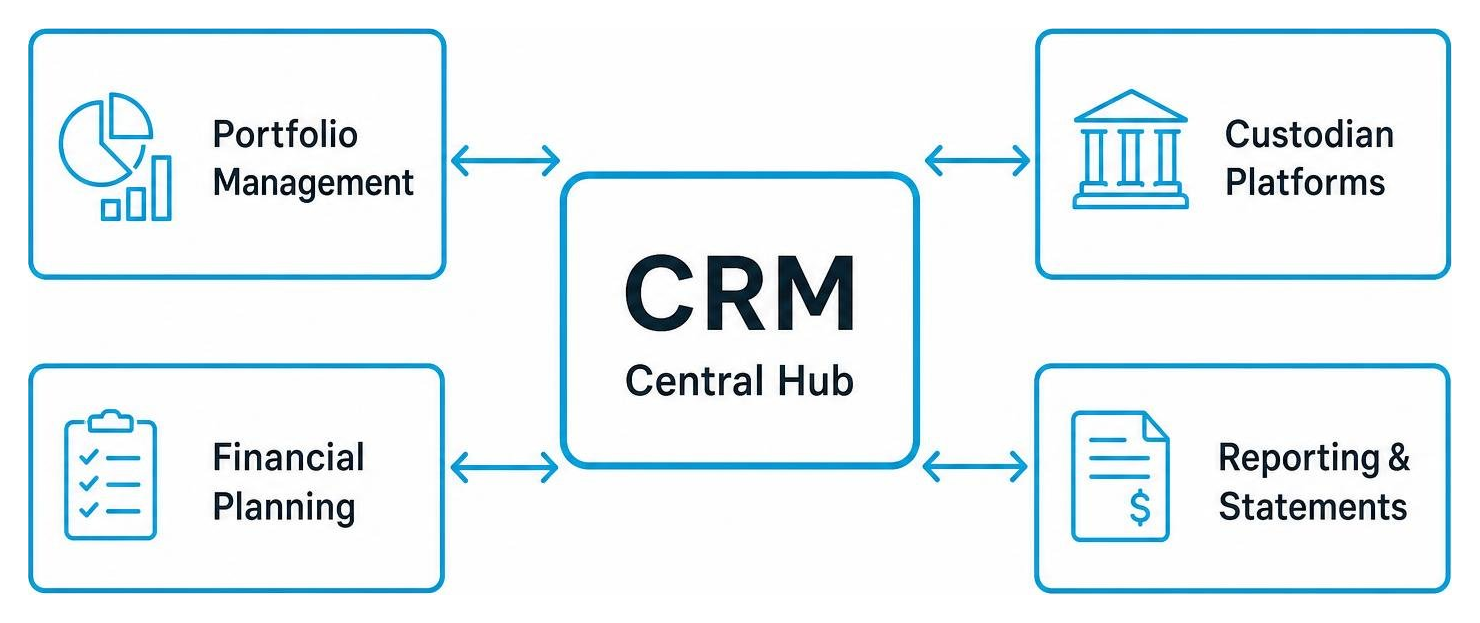
Integrations and CRM architecture are critical because a financial CRM rarely operates alone. It needs to connect with planning tools, portfolio platforms, document systems, email, telephony, analytics, customer portals, identity verification tools, and sometimes core banking or lending systems.
A CRM should act as the central relationship layer of the technology stack. When it is disconnected from core systems, teams waste time copying data between platforms, and leaders lose confidence in reporting. For practical advice, explore our CRM Financial System Integrations Guide and CRM Integration Services Guide.
Designing the Ideal CRM Architecture
The ideal CRM architecture for financial services starts with a clear decision about which system owns each type of data. For example, the CRM may own relationship, activity, opportunity, and service data, while a portfolio platform owns holdings, a planning tool owns advice modelling, and a document system owns formal records.
A strong architecture usually includes:
- A central CRM relationship model for clients, households, entities, advisers, cases, and opportunities.
- Secure integrations to financial planning, portfolio, lending, document, and communication platforms.
- Role-based access rules so sensitive information is visible only to approved users.
- Reporting and analytics layers that use consistent, structured data.
- Governance for data quality, duplicate management, and change control.
This approach helps firms create a 360-degree client view without turning the CRM into an overloaded replacement for every specialist platform.
Connecting to Financial Planning Software
Financial planning software is where advisers model scenarios, calculate projections, and prepare advice documents. By integrating planning tools with the CRM, firms reduce duplicate data entry and keep advice workflows connected to the broader client relationship.
When a client’s contact details, household structure, review dates, or key financial details change, the relevant information can be synchronised or surfaced where advisers need it. This reduces rework and helps ensure advice activity is based on current client information.
Integrating with Portfolio, Custodial, and Lending Platforms
Advisers and relationship managers need visibility into what clients own, borrow, or are applying for. Integrating the CRM with portfolio, custodial, banking, or lending systems can surface account balances, holdings, application statuses, transaction summaries, or other relevant data depending on the firm’s systems and permissions.
The objective is not to copy every detail into the CRM. The objective is to give staff enough context to have informed conversations, manage follow-up tasks, and understand the client relationship without constantly switching systems.
How Are AI, Copilot, and Automation Changing Financial Services CRM?
AI and automation are changing financial services CRM by reducing manual administration, improving follow-up consistency, and helping teams identify where attention may be needed. These capabilities are most useful when they are tied to well-designed workflows, clean data, appropriate licensing, and clear governance.
Artificial intelligence can support practical day-to-day tasks, but firms should avoid assuming every AI feature is automatically available in every Dynamics 365 environment. Capabilities depend on eligible Microsoft Copilot or related Microsoft services licensing, supported channels, configuration, data quality, user permissions, and implementation choices. To explore how CRM data and AI work together, read our article on CRM and Data Analytics.
Reducing Adviser Administration with AI
Advisers often lose significant time to file notes, meeting summaries, action items, follow-up emails, and internal updates. When Microsoft Copilot and related services are appropriately licensed and configured, AI-assisted tools can help summarise meetings, extract action items, draft follow-up communications, and support next-step planning.
These tools do not remove the need for adviser review. In financial services, human oversight remains essential because advice, compliance, suitability, and client context require professional judgement. The value is that AI may reduce repetitive administration so advisers can spend more time on client conversations and fewer hours reconstructing notes after meetings.
Using Microsoft Copilot for Meeting Summaries and Follow-Up Tasks
With eligible licensing and supported Microsoft 365/Dynamics 365 configuration, Copilot-assisted workflows may help capture meeting context, generate structured summaries, and create draft follow-up tasks. This can be useful for annual reviews, loan discussions, onboarding meetings, and service escalations, but output should be reviewed before it is relied on or stored.
A practical implementation should define:
- Which meetings are eligible for transcription or summarisation.
- How summaries are reviewed before being stored.
- Where follow-up tasks are created in the CRM.
- What information should be excluded from AI-generated notes.
- How compliance and privacy requirements are handled.
Predictive Insights and Client Retention Alerts
AI can also analyse historical CRM data to identify patterns, but the quality of the insight depends heavily on data quality and configuration. For example, a firm may configure alerts for clients with reduced interaction frequency, overdue reviews, unresolved service issues, or life events that require proactive outreach.
Used carefully, these insights can help teams prioritise attention and improve client experience. Used poorly, they can create noise, false confidence, or unnecessary tasks. That is why AI should be introduced as part of a broader CRM strategy rather than as a standalone feature.
How to Choose the Right CRM for Your Financial Services Business
Choosing the right CRM for a financial services business means evaluating your firm’s size, services, compliance obligations, technology stack, reporting needs, and growth plans. The best option is not always the most specialised product or the most flexible platform; it is the one that can support your operating model without creating unnecessary complexity.
At Beyond CRM, we help firms design, implement, and optimise tailored Dynamics 365 for Finance and Dynamics 365 Customer Insights solutions. The right decision usually starts with understanding whether your current problem is a platform problem, a configuration problem, a process problem, or a data quality problem.
Do You Need a Specialised Financial CRM?
You likely need a specialised financial CRM configuration if your firm manages households, trusts, entities, advice reviews, regulated onboarding, lending applications, portfolio context, or multi-department service workflows. A generic CRM may still be viable, but it must be configured to reflect those financial services requirements.
Smaller advisory firms may prioritise householding, review workflows, document checklists, and Outlook/Teams integration. Larger institutions may need advanced security, multiple business units, complex reporting, integrations with core platforms, and governance across departments.
Should You Customise Dynamics 365 or Replace It with Industry-Specific Software?
If your firm already uses Microsoft 365, Outlook, Teams, Power BI, or Dynamics 365, customising Dynamics 365 may be more practical than replacing it. The platform can be tailored around financial workflows, integrated with Microsoft services, and extended over time as the firm grows.
However, industry-specific software may be a better fit if your firm needs a narrow, pre-packaged workflow with minimal customisation, limited integration requirements, and a strong preference for out-of-the-box industry templates. The trade-off is that specialised tools can become restrictive if your firm later needs unusual processes, enterprise reporting, or deep Microsoft ecosystem integration.
Decision framework: Choose custom Dynamics 365 when flexibility, integration, reporting, and long-term scalability matter. Consider industry-specific software when speed, simplicity, and a narrow prebuilt workflow matter more than customisation.
What Features Should Financial Firms Prioritise?
The most important CRM features depend on your services, but most financial firms should prioritise:
- Relationship and household mapping.
- Secure client records with role-based access.
- KYC, AML, review, and document workflows.
- Adviser, lending, and service process management.
- Outlook, Teams, document, planning, and portfolio integrations.
- Dashboards for pipeline, service, compliance, and adoption.
- Data quality controls and duplicate management.
- AI-assisted productivity features where licensing and governance allow.
A CRM selection process should score each option against real scenarios, not just a feature checklist. For example, ask vendors to show how the system handles a new advice client, a lending referral, a household relationship, an overdue KYC review, and a service escalation.
Common CRM Implementation Mistakes
One common mistake is treating CRM implementation as a software installation rather than an operational change program. Financial firms need clear workflows, data ownership, migration planning, user training, and adoption support.
Avoid these mistakes:
- Rebuilding every old spreadsheet inside the CRM instead of simplifying the process.
- Customising too heavily before validating what users actually need.
- Ignoring data quality and duplicate records during migration.
- Failing to define security roles and compliance requirements early.
- Launching without practical training based on real financial services scenarios.
- Measuring success only by go-live completion rather than adoption, data quality, and process improvement.
How to Improve CRM Adoption
CRM adoption improves when users see that the system helps them do their job rather than adding extra administration. Advisers, brokers, and service teams need workflows that match real client interactions, not generic screens full of irrelevant fields.
A strong adoption plan usually includes early user involvement, simple first-release workflows, role-specific training, executive sponsorship, and visible reporting on usage and outcomes. It should also include feedback loops after launch so the CRM can be refined as teams discover what works in practice.
Frequently Asked Questions About Financial Services CRMs
Can one CRM support advisers, lending, banking, and customer service teams?
Yes, one CRM can support multiple departments if it is designed with shared client records, role-specific workflows, appropriate security, and clear data ownership. Advisers, lending teams, banking staff, and customer service teams do not need identical screens or processes, but they do need a consistent view of the client relationship.
Can we use Microsoft Dynamics 365 for financial services?
Yes. Microsoft Dynamics 365 can provide a secure, scalable foundation for financial services, but it should usually be tailored with industry-specific data models, householding, compliance workflows, integrations, and reporting. Partnering with specialists like Beyond CRM helps ensure the platform is configured around the firm’s operating model.
How does a financial CRM handle data privacy regulations?
A robust financial CRM supports privacy requirements through role-based access control, field-level security, encryption, data retention processes, and audit logs. The exact configuration should reflect the firm’s regulatory obligations, internal policies, and jurisdictions.
What is the typical timeline for implementing a new financial CRM?
The timeline varies based on firm size, data complexity, integrations, and workflow requirements. A focused implementation for a smaller advisory firm may take weeks, while an enterprise rollout involving multiple departments and financial systems can take several months. A phased approach often reduces risk and improves adoption.
What should we ask before speaking with a CRM consultant?
Before contacting a consultant, clarify which teams will use the CRM, where client data currently lives, what processes are manual, which systems need integration, what compliance tasks must be tracked, and what reports leadership needs. These answers help shape a more accurate CRM design and implementation plan.
Build a Financial Services CRM That Supports Better Decisions
A financial services CRM should help your team manage complex relationships, protect sensitive data, coordinate compliance activity, and deliver consistent service across advice, lending, banking, and support teams. The strongest CRM strategies start by understanding the firm’s operating challenges first, then designing the platform, workflows, integrations, and reporting around those needs.
Key takeaway: The right CRM design creates a connected operating model for client data, compliance, service, and growth.
If your current systems are fragmented, difficult to report on, or too generic for financial services, Beyond CRM can help you assess your current setup and design a Dynamics 365 solution that fits your client lifecycle.
Next steps:


